Eleven years, two languages, one desk
I started as a processor, which is an unglamorous way to learn this job and the best one. It means I read guidelines the way underwriters do, and I know which files will be a problem before anyone else does.
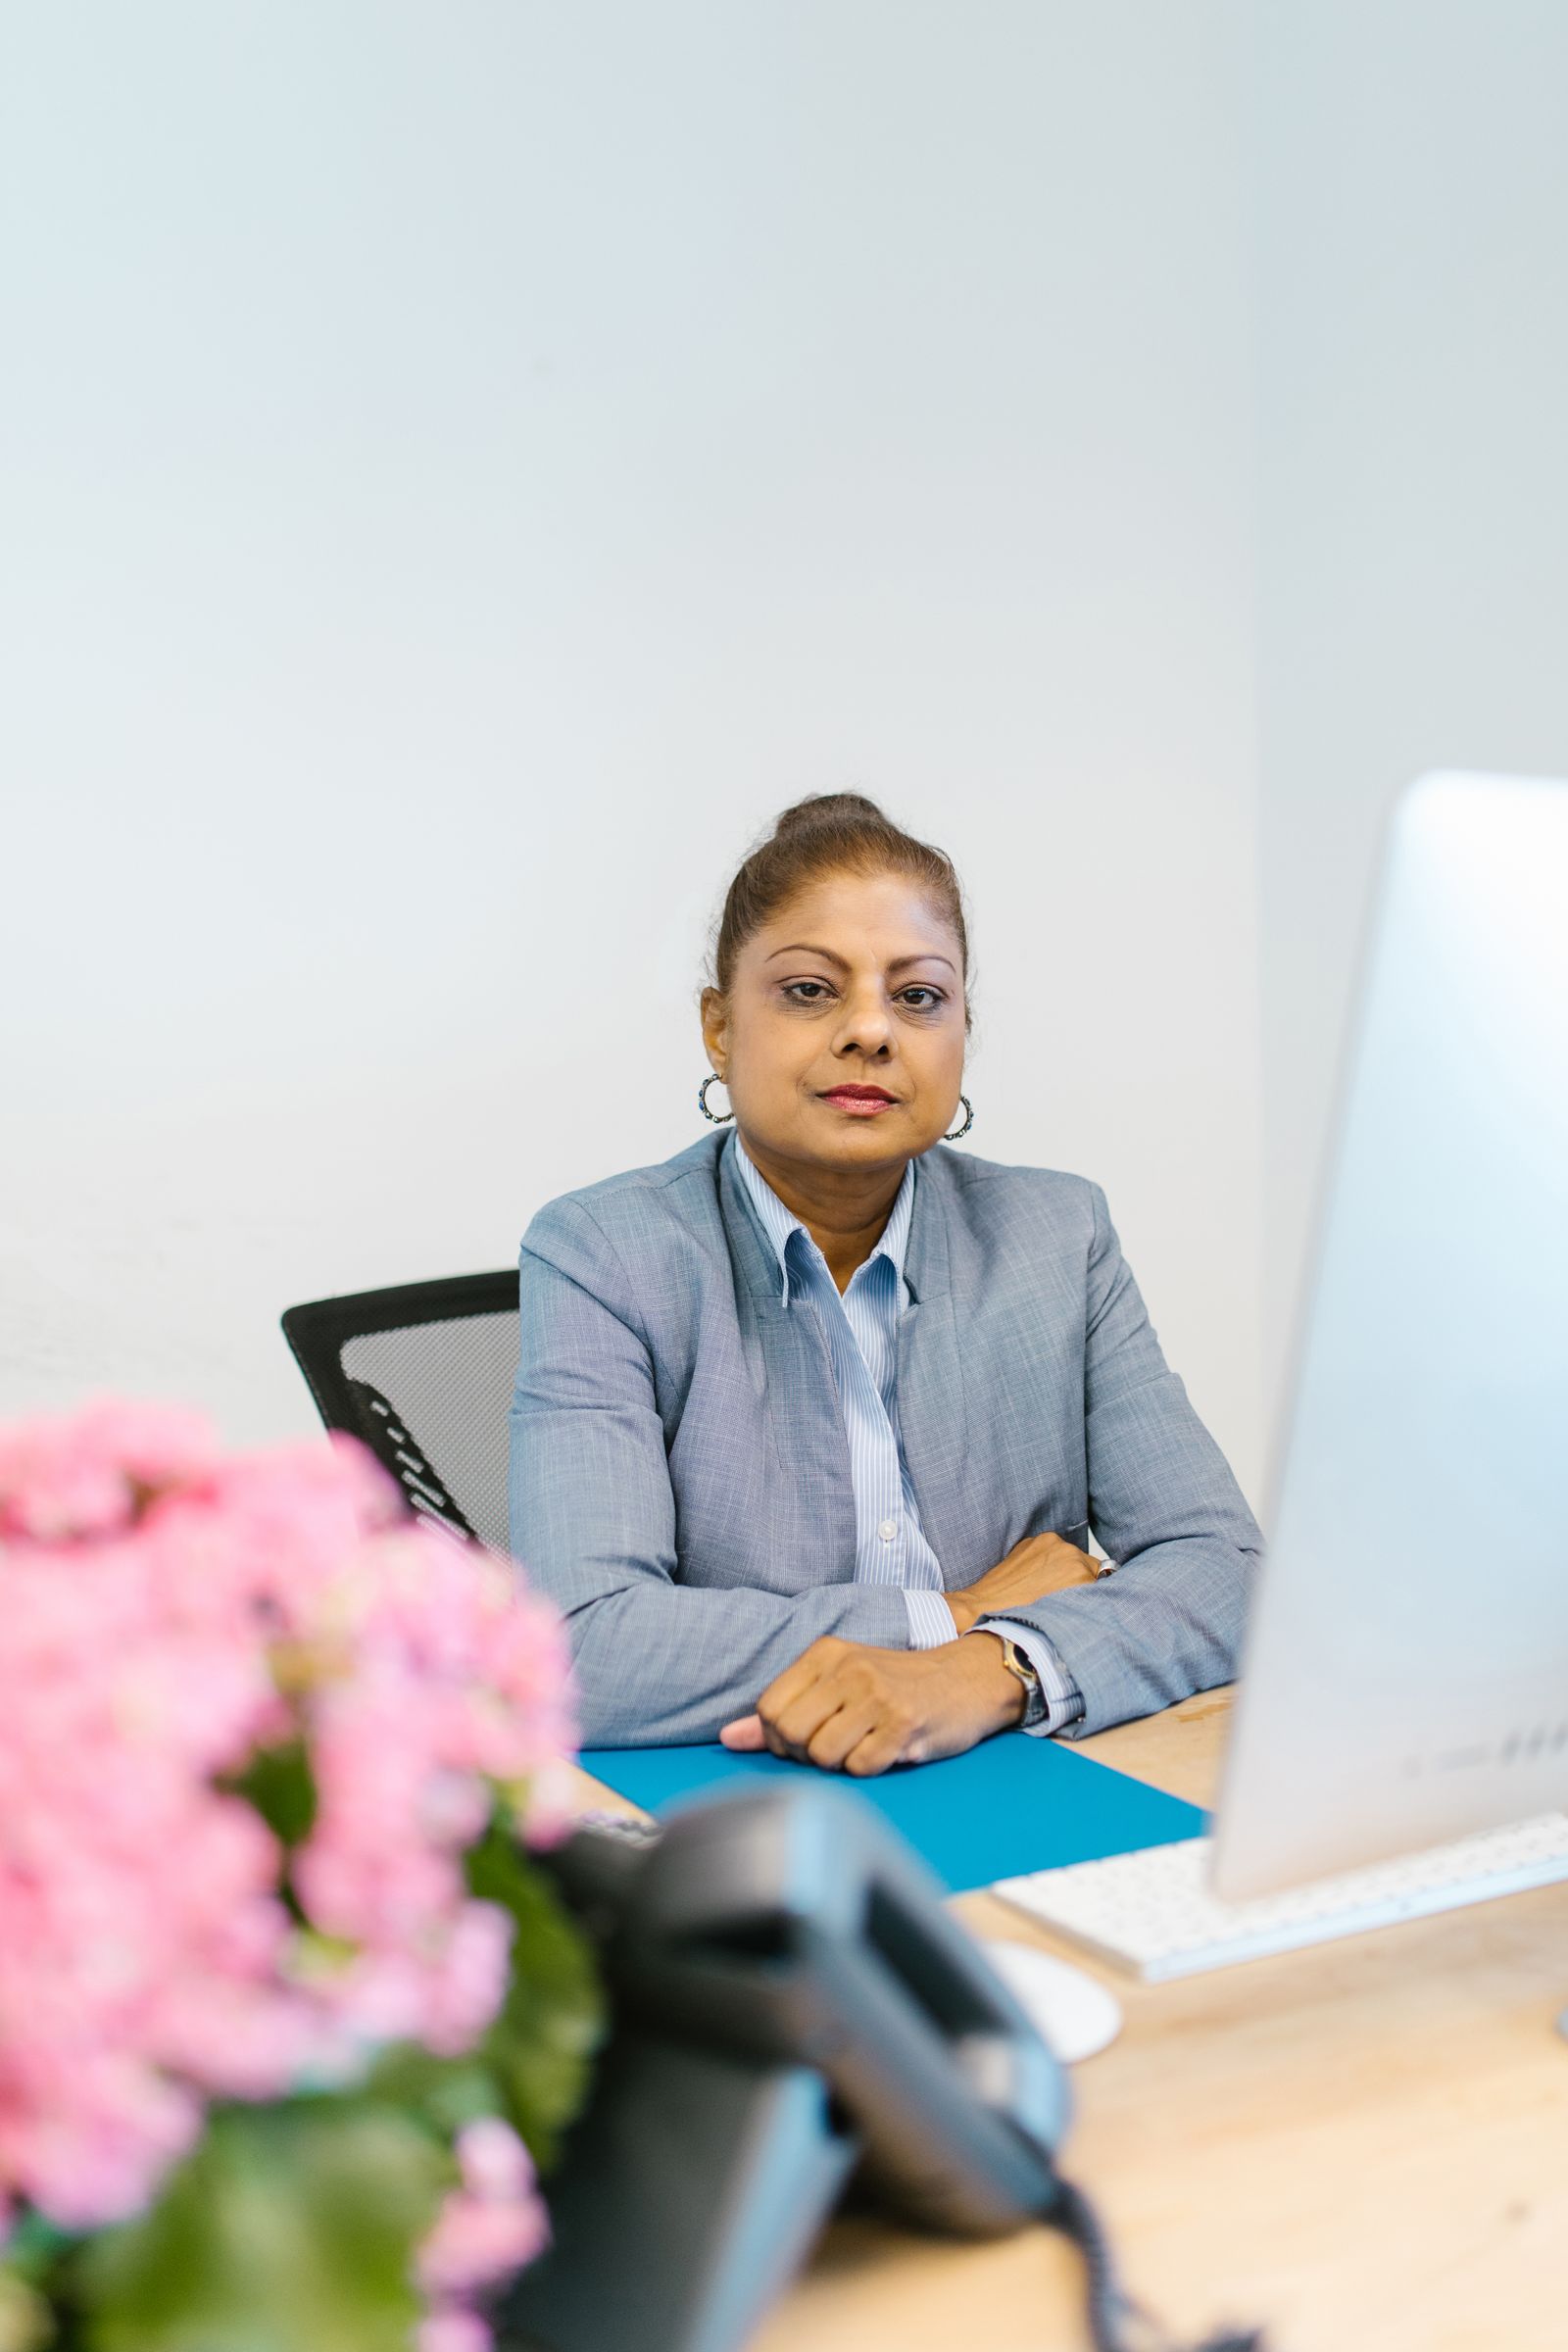
How I ended up doing this
My parents bought their first house in Milpitas in 1998 with a loan officer who never returned a call. I watched my father photocopy the same bank statements three times because nobody kept a list. That is a small thing, and it is also the reason I do this job the way I do.
I processed files for three years before I was licensed. Processing is where you learn what an underwriter is actually looking for, which is not the same as what a sales script says. By the time I took my own first client in 2018, I had already seen four hundred files come apart and knew exactly where the cracks form.
These days most of my work involves income that does not fit a standard form: restricted stock, bonus history, twelve months of deposits, a portfolio instead of a paycheck. Those files are not harder. They just need someone who will spend an hour on the structure before anyone pulls credit.
- 2015Started as a loan processor in Santa Clara, reading guidelines for a living.
- 2018Licensed as a loan officer and closed the first jumbo file on my own name.
- 2021Built the equity income process after a fifth client was quoted off base salary alone.
- 2026640+ families financed, 4.9 average from 187 reviews.
Four rules I do not bend
Everything else about a mortgage is negotiable. These are not.
Tell people the truth early
If a program will not work, you hear it on the first call rather than three weeks into an escrow. I would rather lose a file than watch one fall apart in week four.
Build the file before the pressure
Underwriting before you shop is not extra work, it is the work. Everything after acceptance is easier when the hard part is already approved.
Explain it in the family's language
Parents and in laws often help with the down payment here. They deserve the explanation too, in English, Tamil or Hindi, without being talked past.
Answer the phone
Listing agents get a call back the same hour. Clients get my mobile. Nobody on my files has ever had to chase a status update from a portal.
The four people on your file
You work with me. Amira, Josh and Nikhil make sure nothing sits waiting, and you will meet all of them.
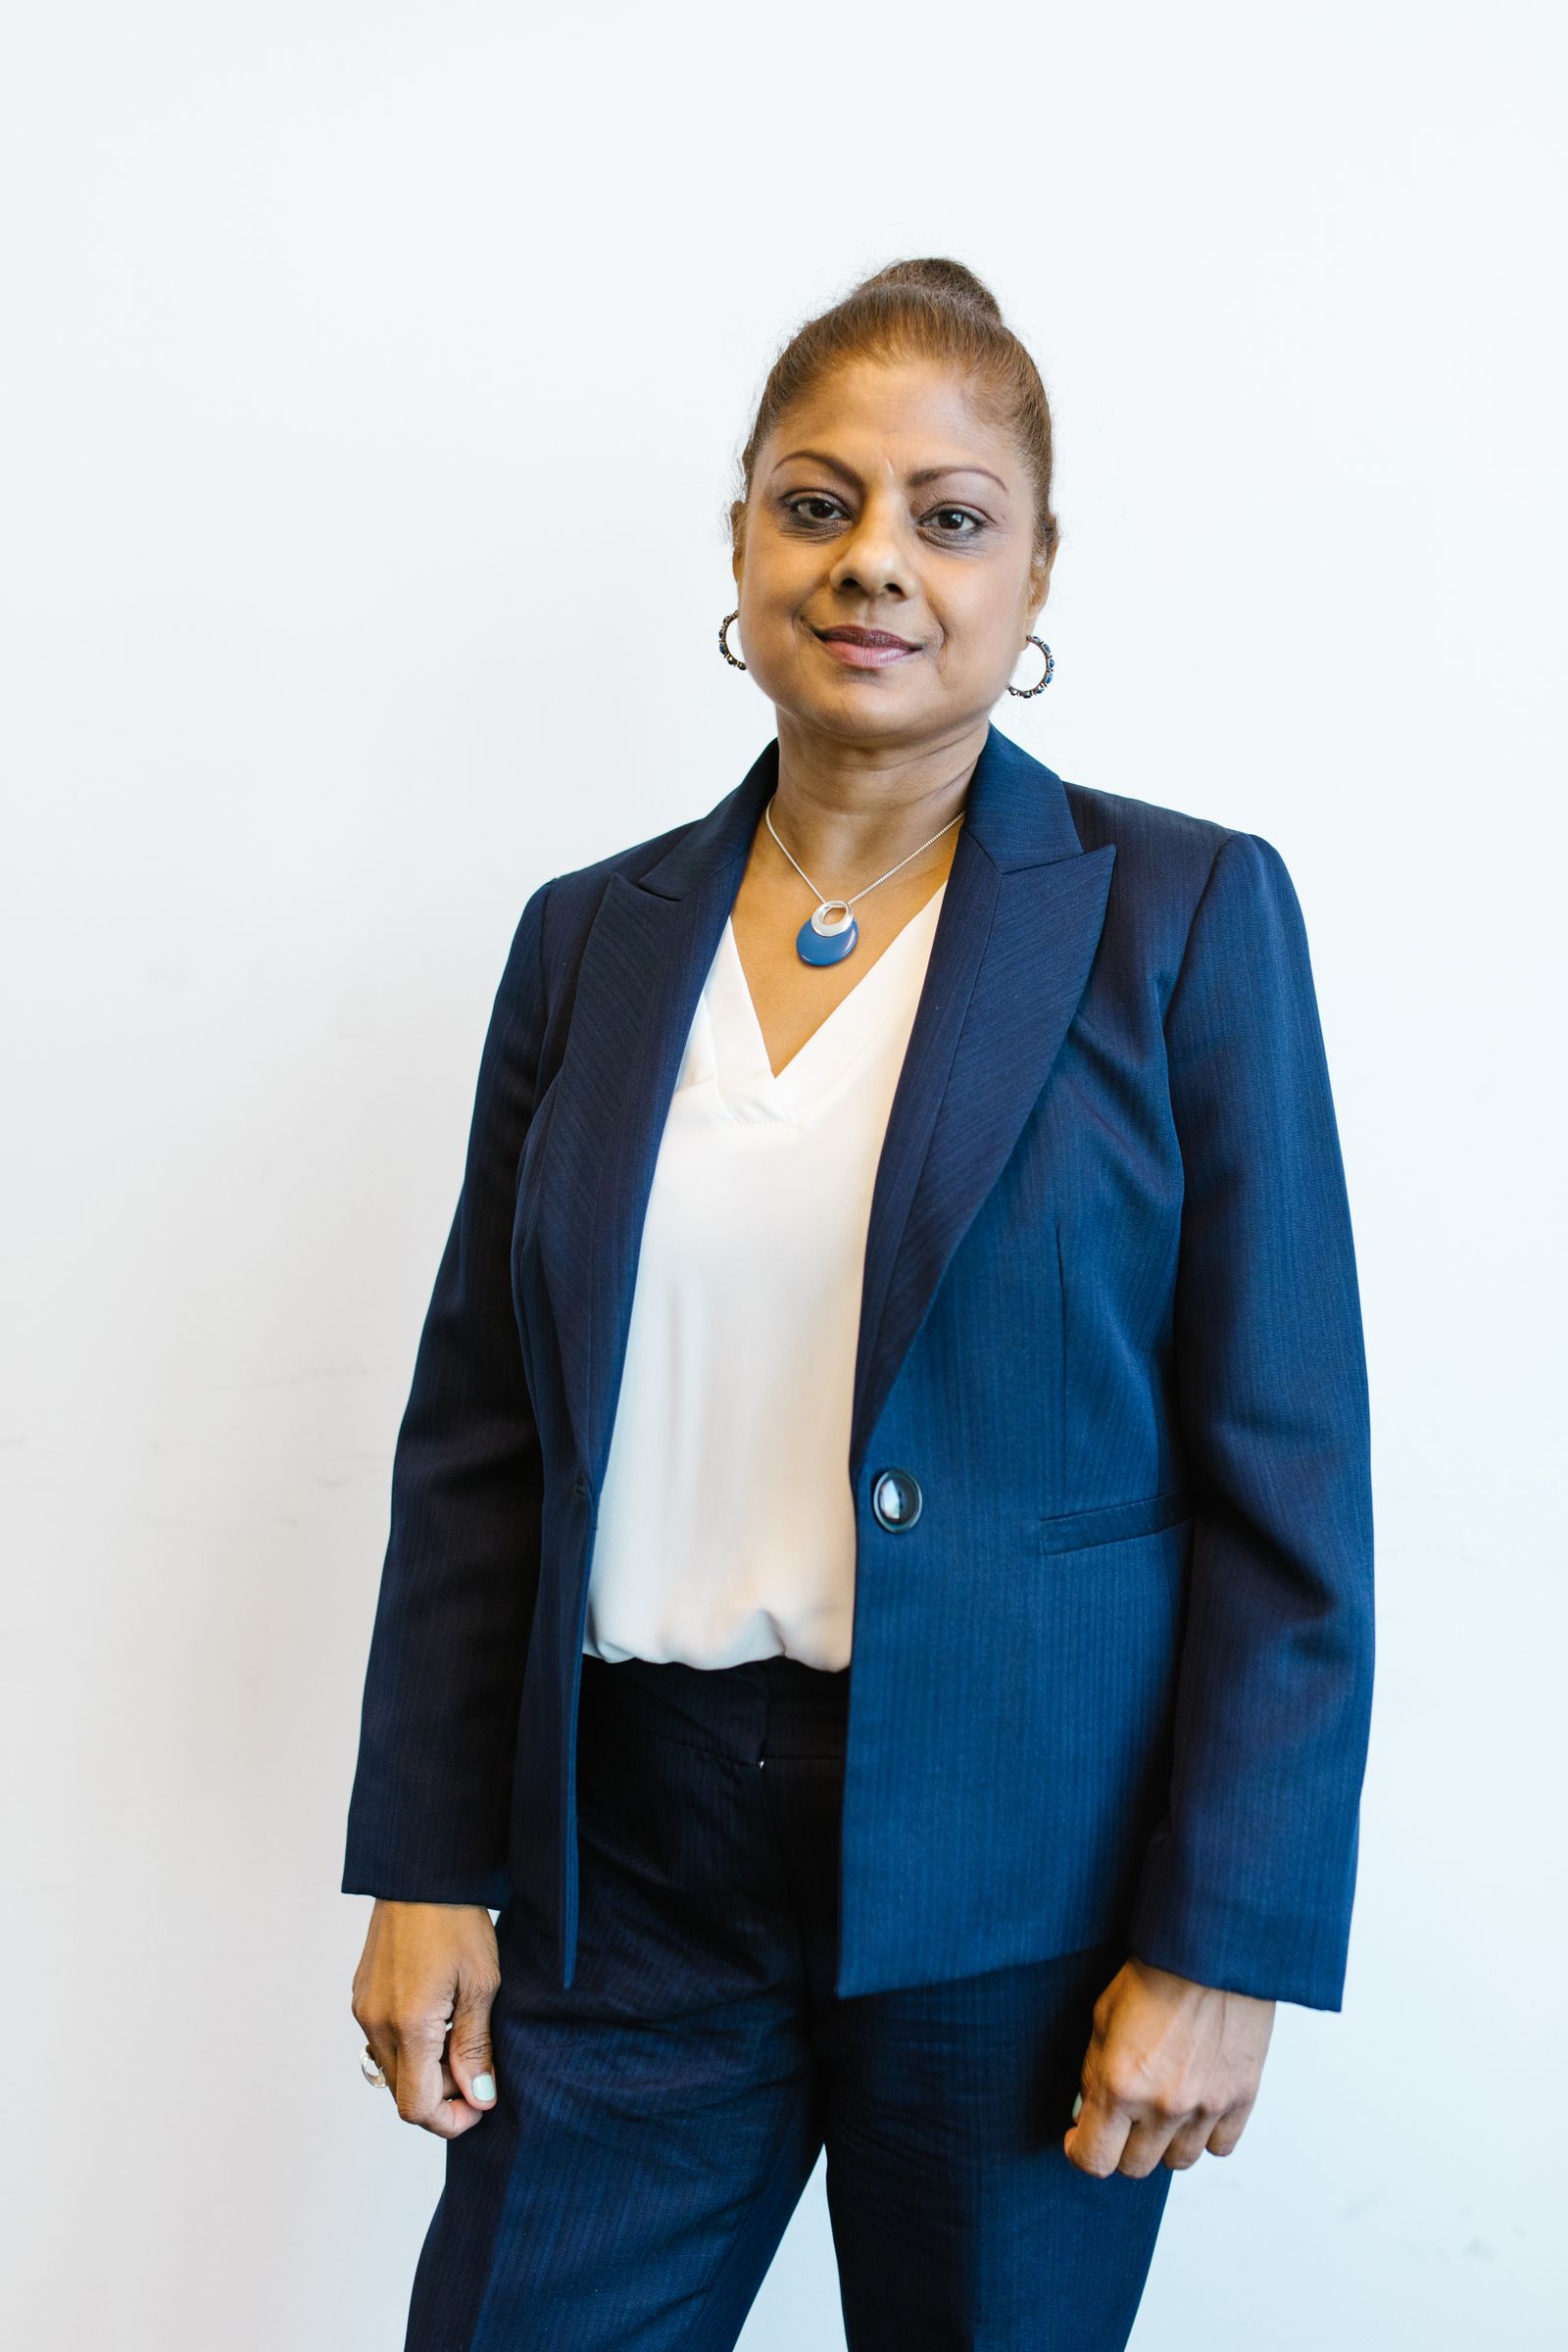
Priya started as a processor in 2015, which is why she reads guidelines the way underwriters do. She works directly with every client from the first call through signing, in English, Tamil and conversational Hindi.
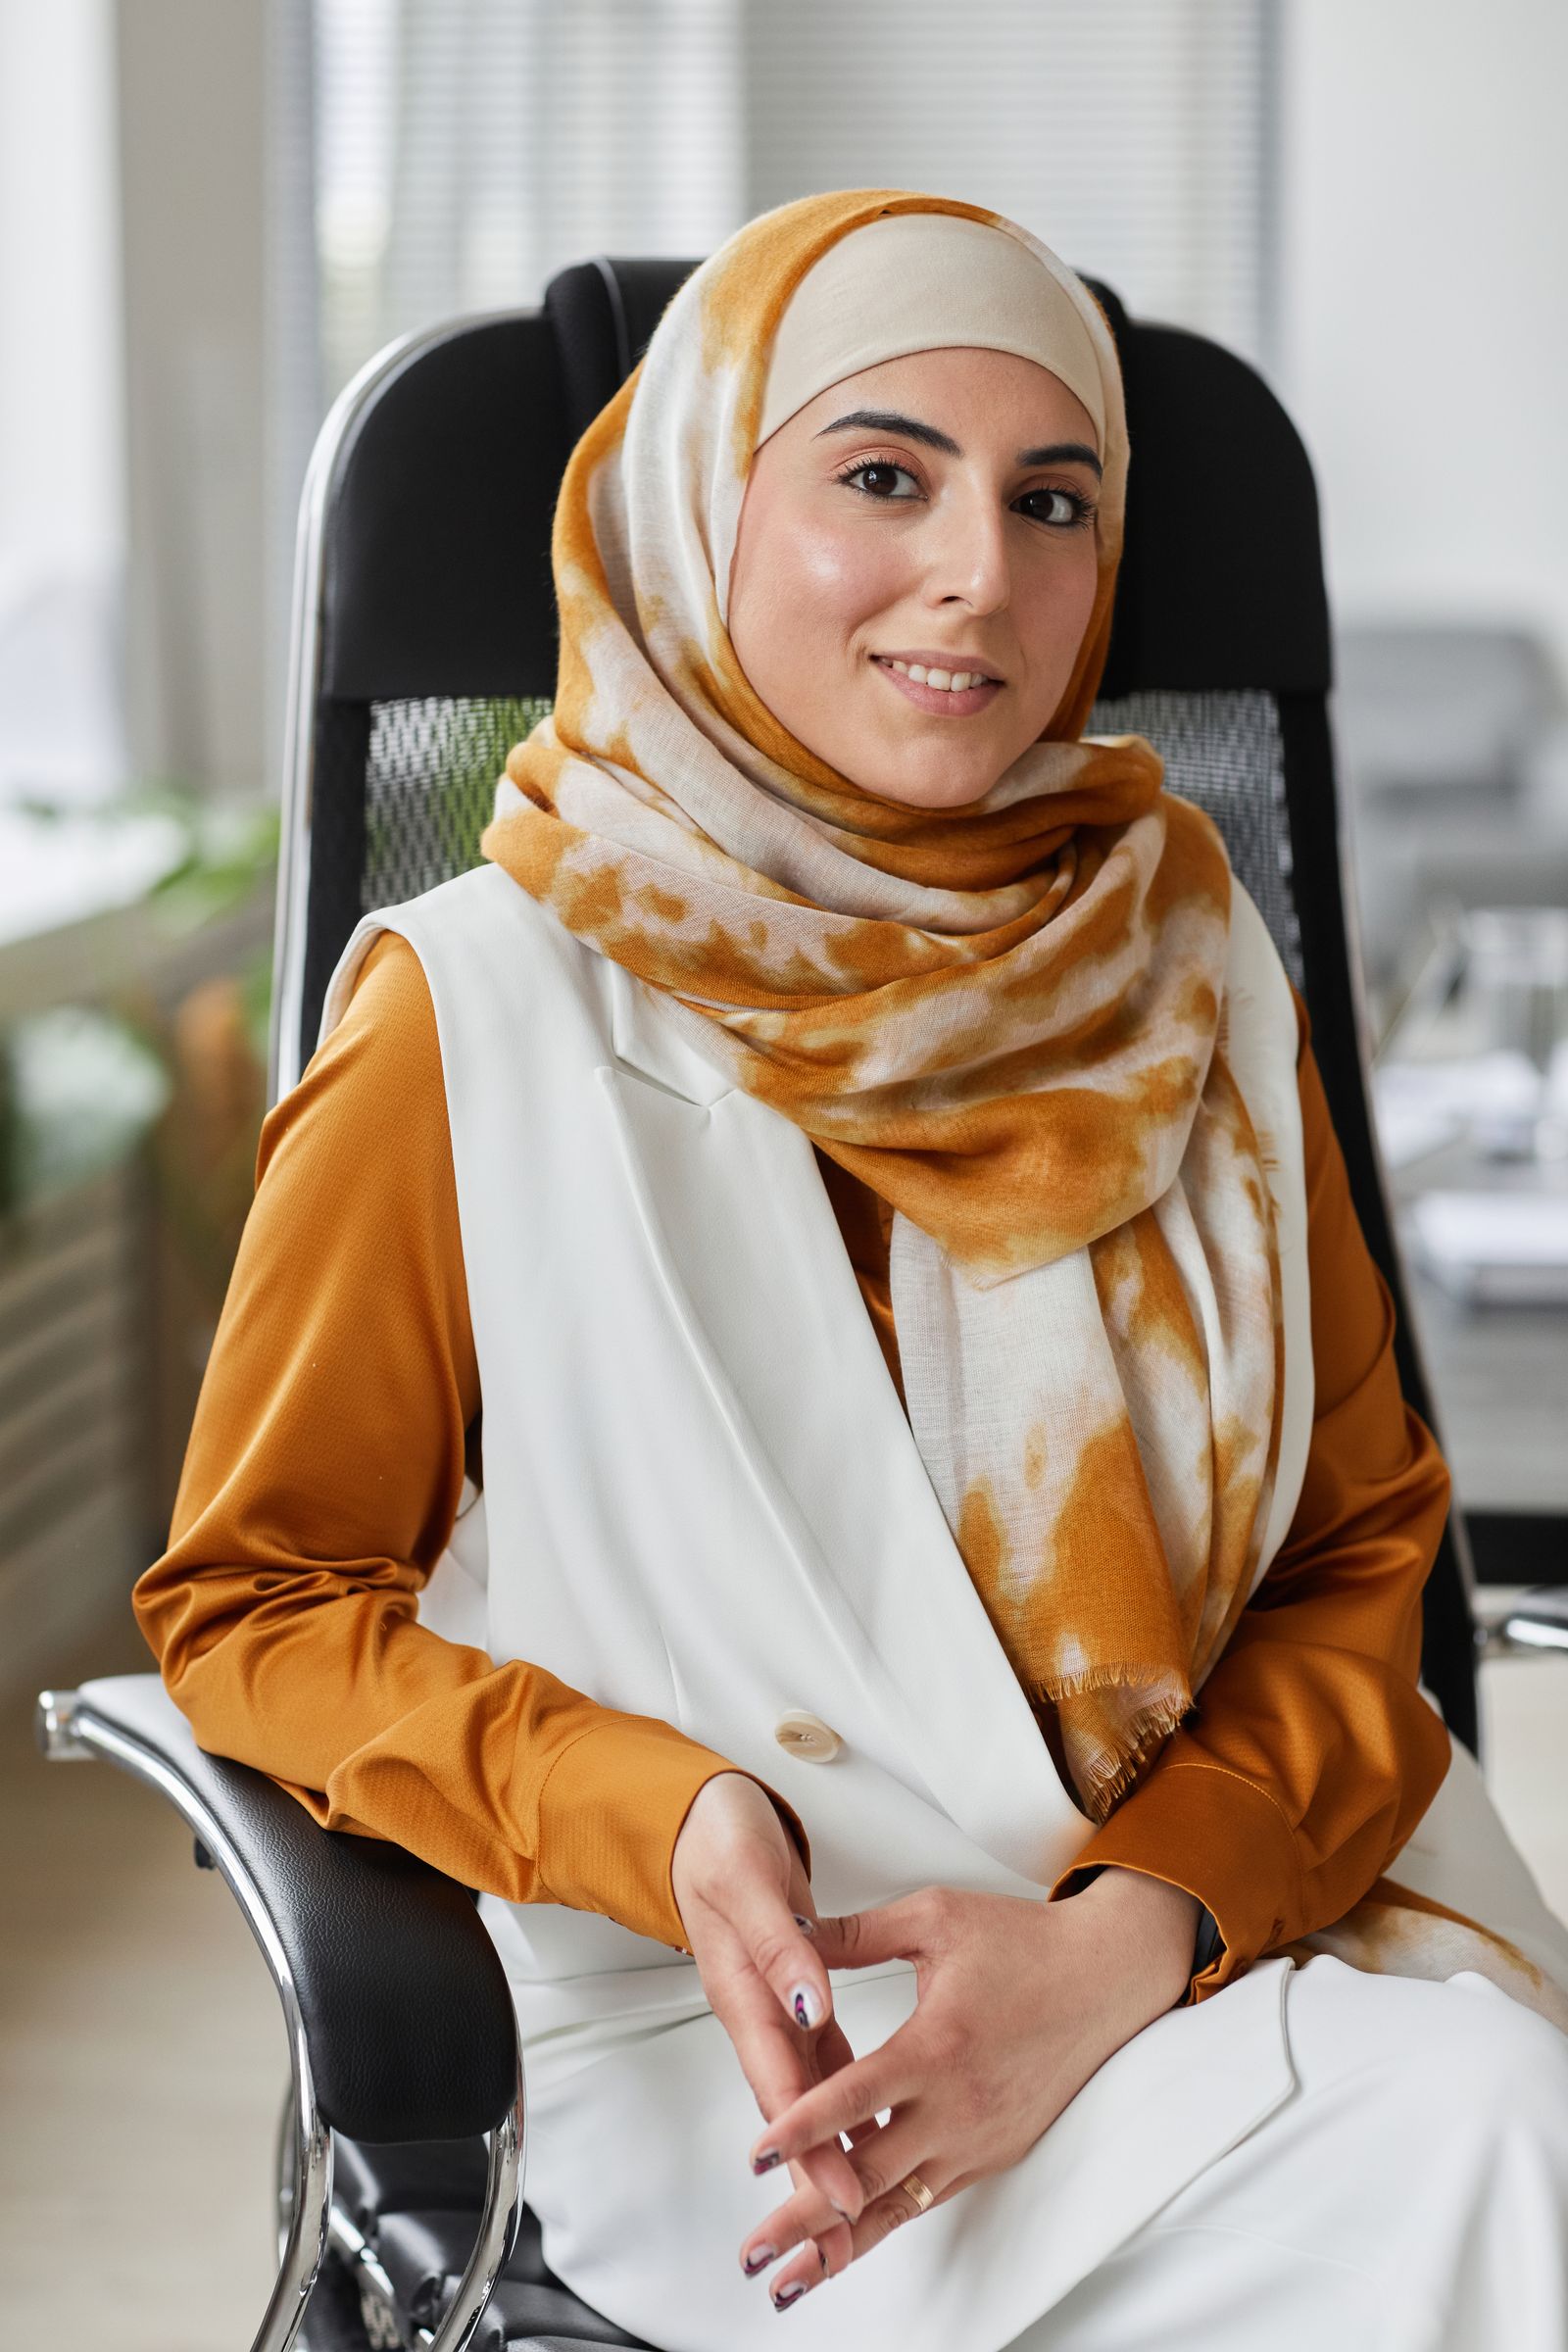
Amira has processed more than 1,100 files. She builds the condition list the day the approval lands and chases title, escrow and insurance so you are not the one following up.
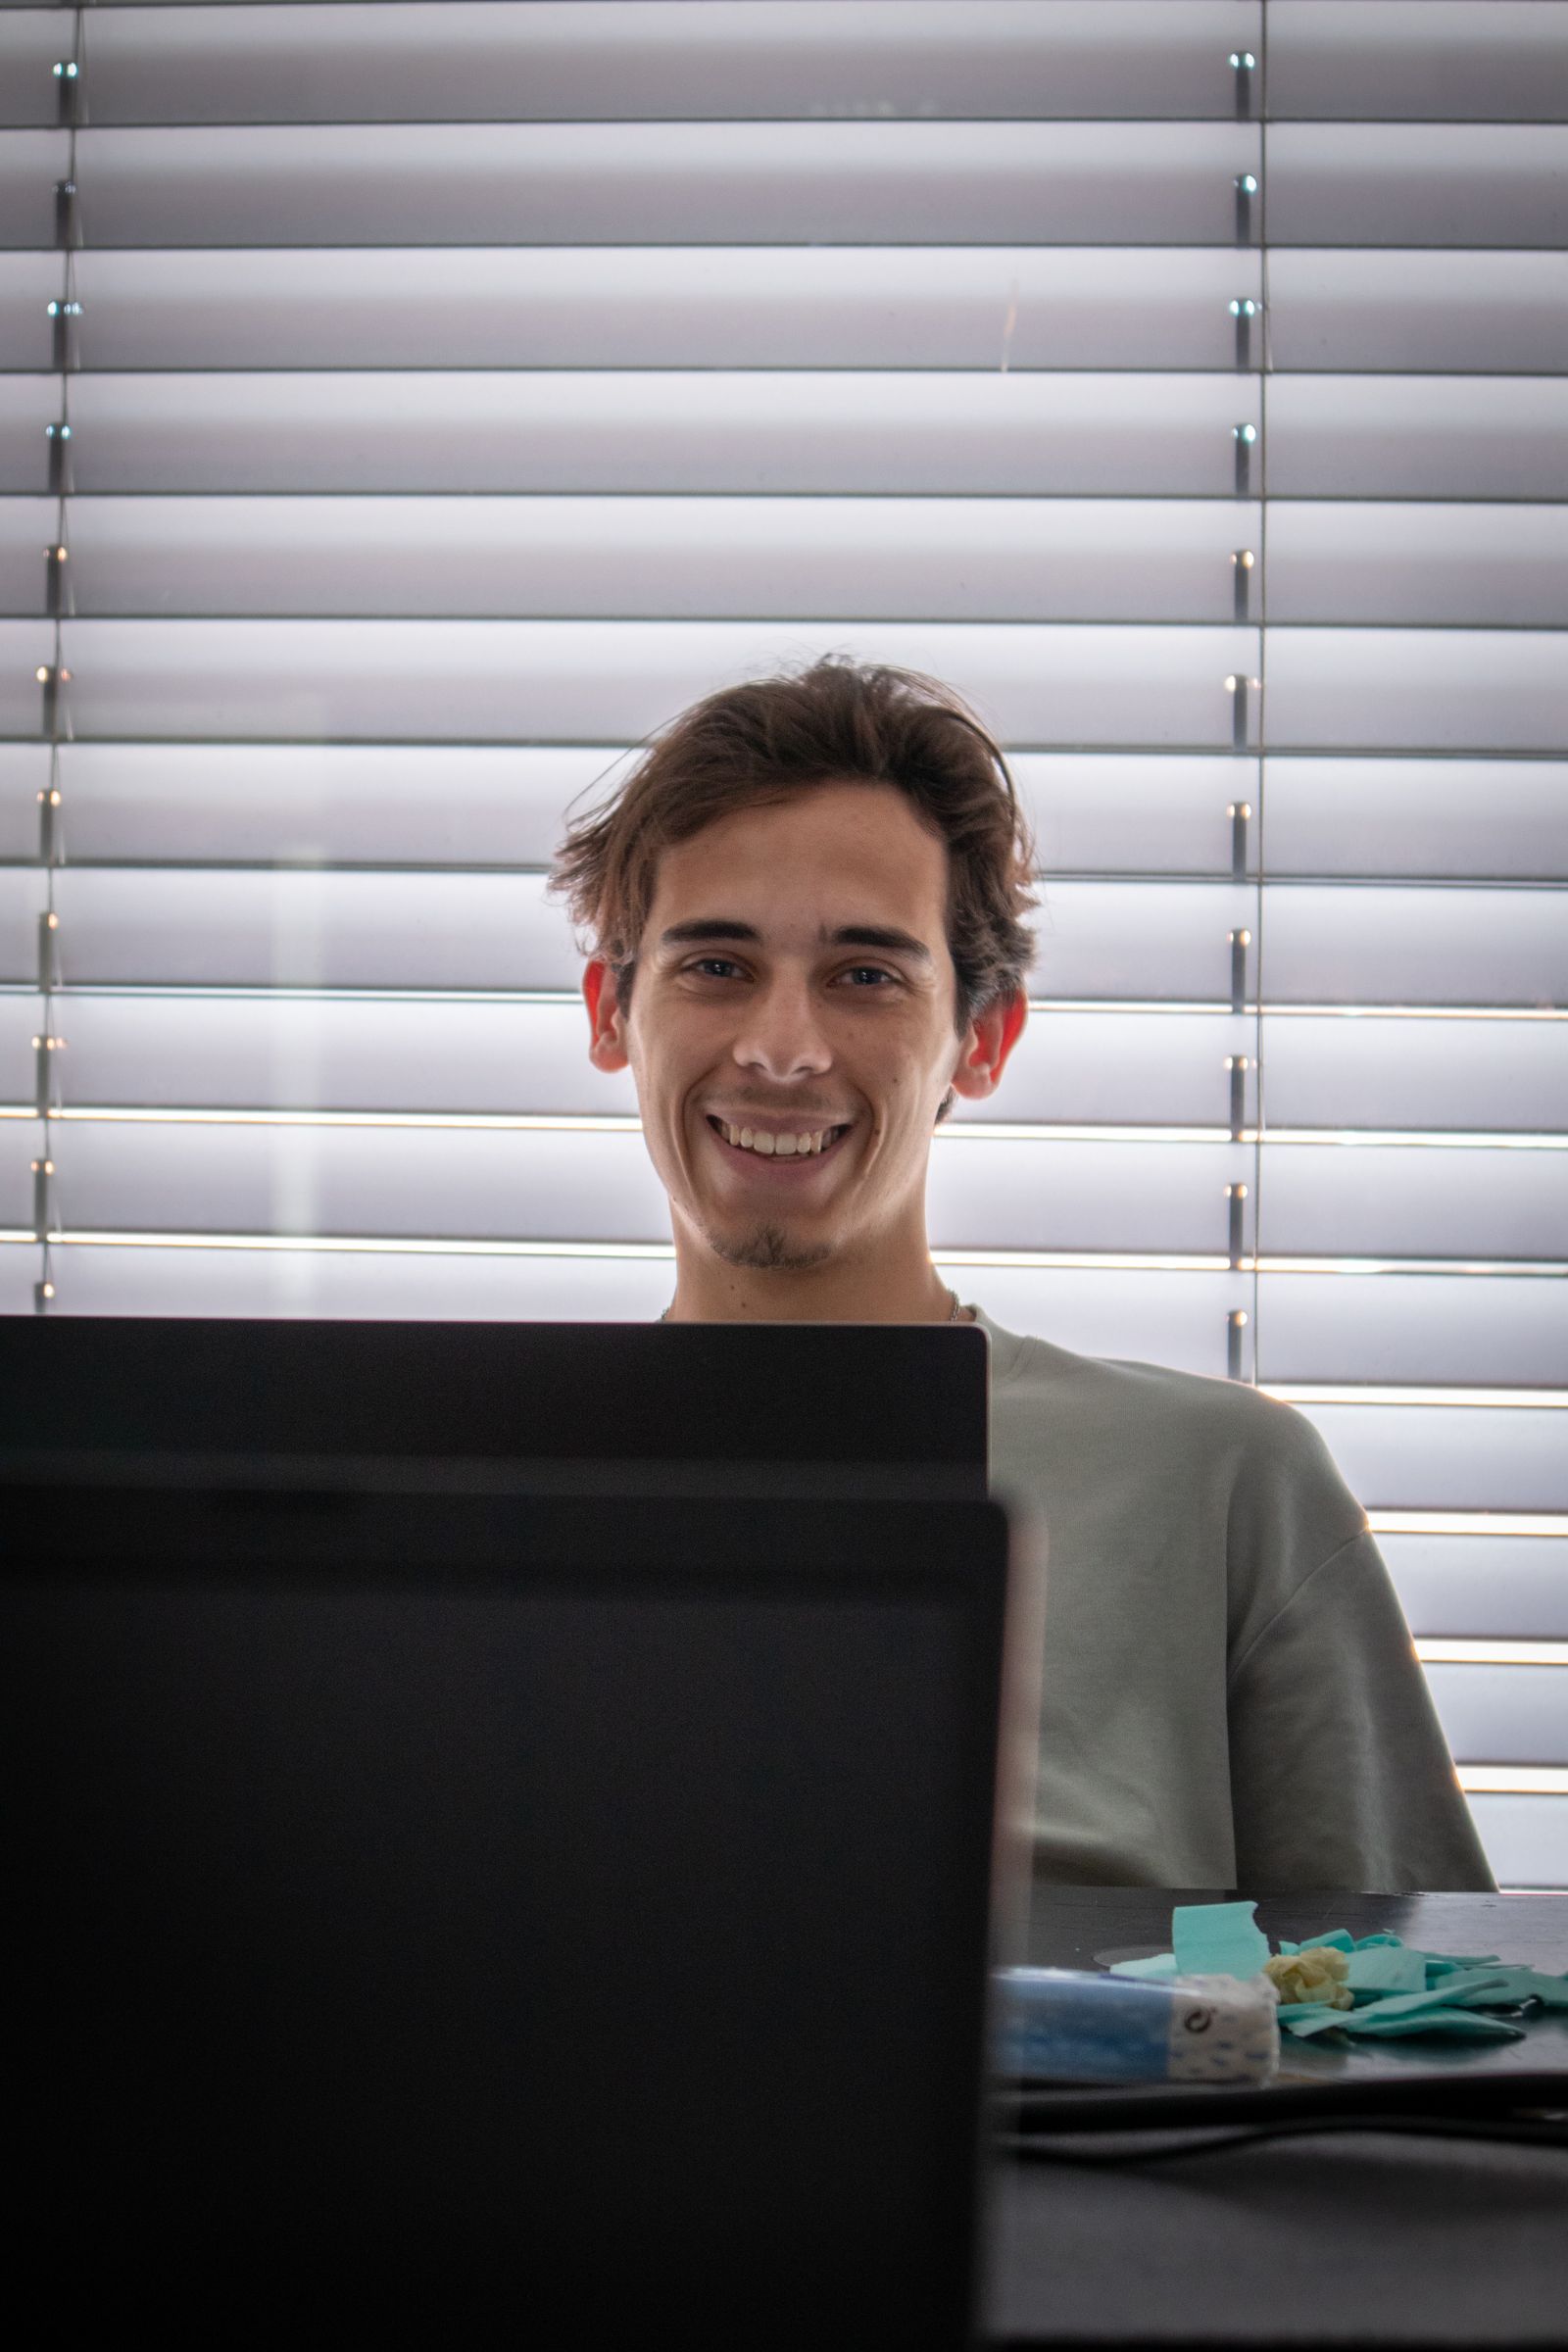
Josh sets up your secure portal, tells you exactly which statement pages are needed and which are not, and answers the small questions quickly so they never turn into delays.
Nikhil watches appraisal, contingency and signing dates against the contract so your agent always knows where the loan stands without having to ask.
Every license number on this demo is a placeholder. On a real site they would be verifiable.
Credentials and the fine print
The licensing details, kept where you can find them rather than buried in a footer.
- Licensed in California: DRE and NMLS registered, sample license numbers shown on the licensing page.
- Certified Mortgage Advisor: Continuing education completed annually since 2017.
- Equal Housing Opportunity: Fair lending practices on every file, without exception.
- Santa Clara County focus: More than 640 families financed inside the county since 2015.
NMLS #0000000 (sample placeholder). Licensed by the California Department of Financial Protection and Innovation. Equal Housing Opportunity.
Licensing and disclosures
Twenty minutes, no documents
The first call is a conversation about your situation. Nothing gets pulled, nothing gets submitted.
Sample figures across this site are illustrations, not quotes. Equal Housing Opportunity.