A call before anything else
Twenty minutes, no documents, no credit pull. We talk about how you are paid, what you have saved and the payment you actually want to live with, which is usually lower than what you qualify for.
NMLS #0000000 (sample placeholder) · Equal Housing Opportunity
I am Priya Raman. I structure Bay Area purchases and refinances around how you are actually paid, whether that is salary, restricted stock, deposits or a portfolio. You get my direct line, not a queue.
NMLS #0000000 (sample placeholder) · Equal Housing Opportunity · Figures shown across this site are samples, not quotes.
4.9 from 187 client reviews
Four steps, in this order, every time. You always know which one you are in.
Twenty minutes, no documents, no credit pull. We talk about how you are paid, what you have saved and the payment you actually want to live with, which is usually lower than what you qualify for.
Income, assets and reserves organised the way an underwriter reads them. If you have equity income or twelve months of deposits instead of pay stubs, this is the step that decides your number.
A real underwriter approves the file subject to a property. That letter, plus a call from me to the listing agent, is what makes an offer believable in this county.
Appraisal ordered within a day of acceptance, conditions cleared as they arrive, and closing figures in your inbox two days before signing so the notary holds no surprises.
Restricted stock, ESPP shares and bonuses are countable income on most of the programs I use, with the right history and the right lender. Quote you off base salary alone and you lose a third of your buying power.
Two year vesting history and three years of remaining schedule is the usual test
Trailing share price averages protect you in a volatile quarter
Sale timing planned so your down payment is never an unsourced deposit
Above the county conforming cap there is no automated approval. An underwriter reads the whole story, which means an organised file with the reserves and appraisal handled early simply closes faster.
Reserve planning that counts retirement and vested equity correctly
Second appraisals ordered on day one above two million
Down payment tiers compared at 10, 15, 25 and 30 percent before you choose
What the same buyer might see across four programs on the same day. Figures are illustrations for this demo site.
| Program | Sample rate | Sample APR | Points | Fits best |
|---|---|---|---|---|
| 30 year conforming30 year fixed | 6.125% | 6.284% | 0.5 | Loan amounts to $1,209,750 in Santa Clara County |
| 30 year jumbo30 year fixed | 6.250% | 6.341% | 0.25 | Purchase prices from $1.4M to $3M |
| 7/6 jumbo ARM7 year fixed period | 5.750% | 6.102% | 0.25 | Buyers who expect to move or refinance inside seven years |
| FHA 30 year30 year fixed | 5.875% | 6.762% | 0.5 | Credit rebuilding or a 3.5% down payment |
30 year conforming30 year fixed
Loan amounts to $1,209,750 in Santa Clara County
30 year jumbo30 year fixed
Purchase prices from $1.4M to $3M
7/6 jumbo ARM7 year fixed period
Buyers who expect to move or refinance inside seven years
FHA 30 year30 year fixed
Credit rebuilding or a 3.5% down payment
Sample figures for illustration only. Not an offer to lend or a rate lock. Actual pricing depends on credit, loan amount, property, occupancy, term and the market on the day you lock. Sheet dated September 2026 (sample).
Points, market pricing or a lender credit. The right one depends on how long you will keep the loan, not on which number looks smallest.
A slightly higher rate that pays part of your closing costs back to you at the table.
6.625%6.688% APR (sample)
No discount points
Lowest cash needed at signing
Best for a short hold or an expected refinance
The straight rate with no points added and no credit taken. What most of my buyers choose.
6.250%6.341% APR (sample)
Balanced rate and closing cost
Appraisal ordered day one
Float down if the market improves before you lock
Money paid up front to buy the rate down for the life of the loan.
5.875%6.104% APR (sample)
Lowest monthly payment
Break even usually inside five years
Best when you plan to stay put
Sample $1,000,000 loan, 30 year fixed, 25% down, 780 credit score, single family primary residence in San Jose. Sample figures for illustration only. Not an offer to lend or a rate lock. Actual pricing depends on credit, loan amount, property, occupancy, term and the market on the day you lock.
A slightly higher rate that pays part of your closing costs back to you at the table.
6.500%6.561% APR (sample)
No discount points
Lowest cash needed at signing
Best for a short hold or an expected refinance
The straight rate with no points added and no credit taken. What most of my buyers choose.
6.000%6.147% APR (sample)
Balanced rate and closing cost
Appraisal ordered day one
Float down if the market improves before you lock
Money paid up front to buy the rate down for the life of the loan.
5.625%5.874% APR (sample)
Lowest monthly payment
Break even usually inside five years
Best when you plan to stay put
Sample $800,000 loan, 30 year fixed, 65% loan to value, 780 credit score, single family primary residence in San Jose. Sample figures for illustration only. Not an offer to lend or a rate lock. Actual pricing depends on credit, loan amount, property, occupancy, term and the market on the day you lock.
No portal ping pong and no request for the same document twice.
Eight items, one secure upload, usually collected in a single evening. Josh will tell you exactly which statement pages matter.
Self employed? Send twelve or twenty four months of bank statements instead of tax returns and we will work from deposits.
Start my applicationYou work with me. Amira, Josh and Nikhil make sure nothing sits waiting, and you will meet all of them.
Priya started as a processor in 2015, which is why she reads guidelines the way underwriters do. She works directly with every client from the first call through signing, in English, Tamil and conversational Hindi.
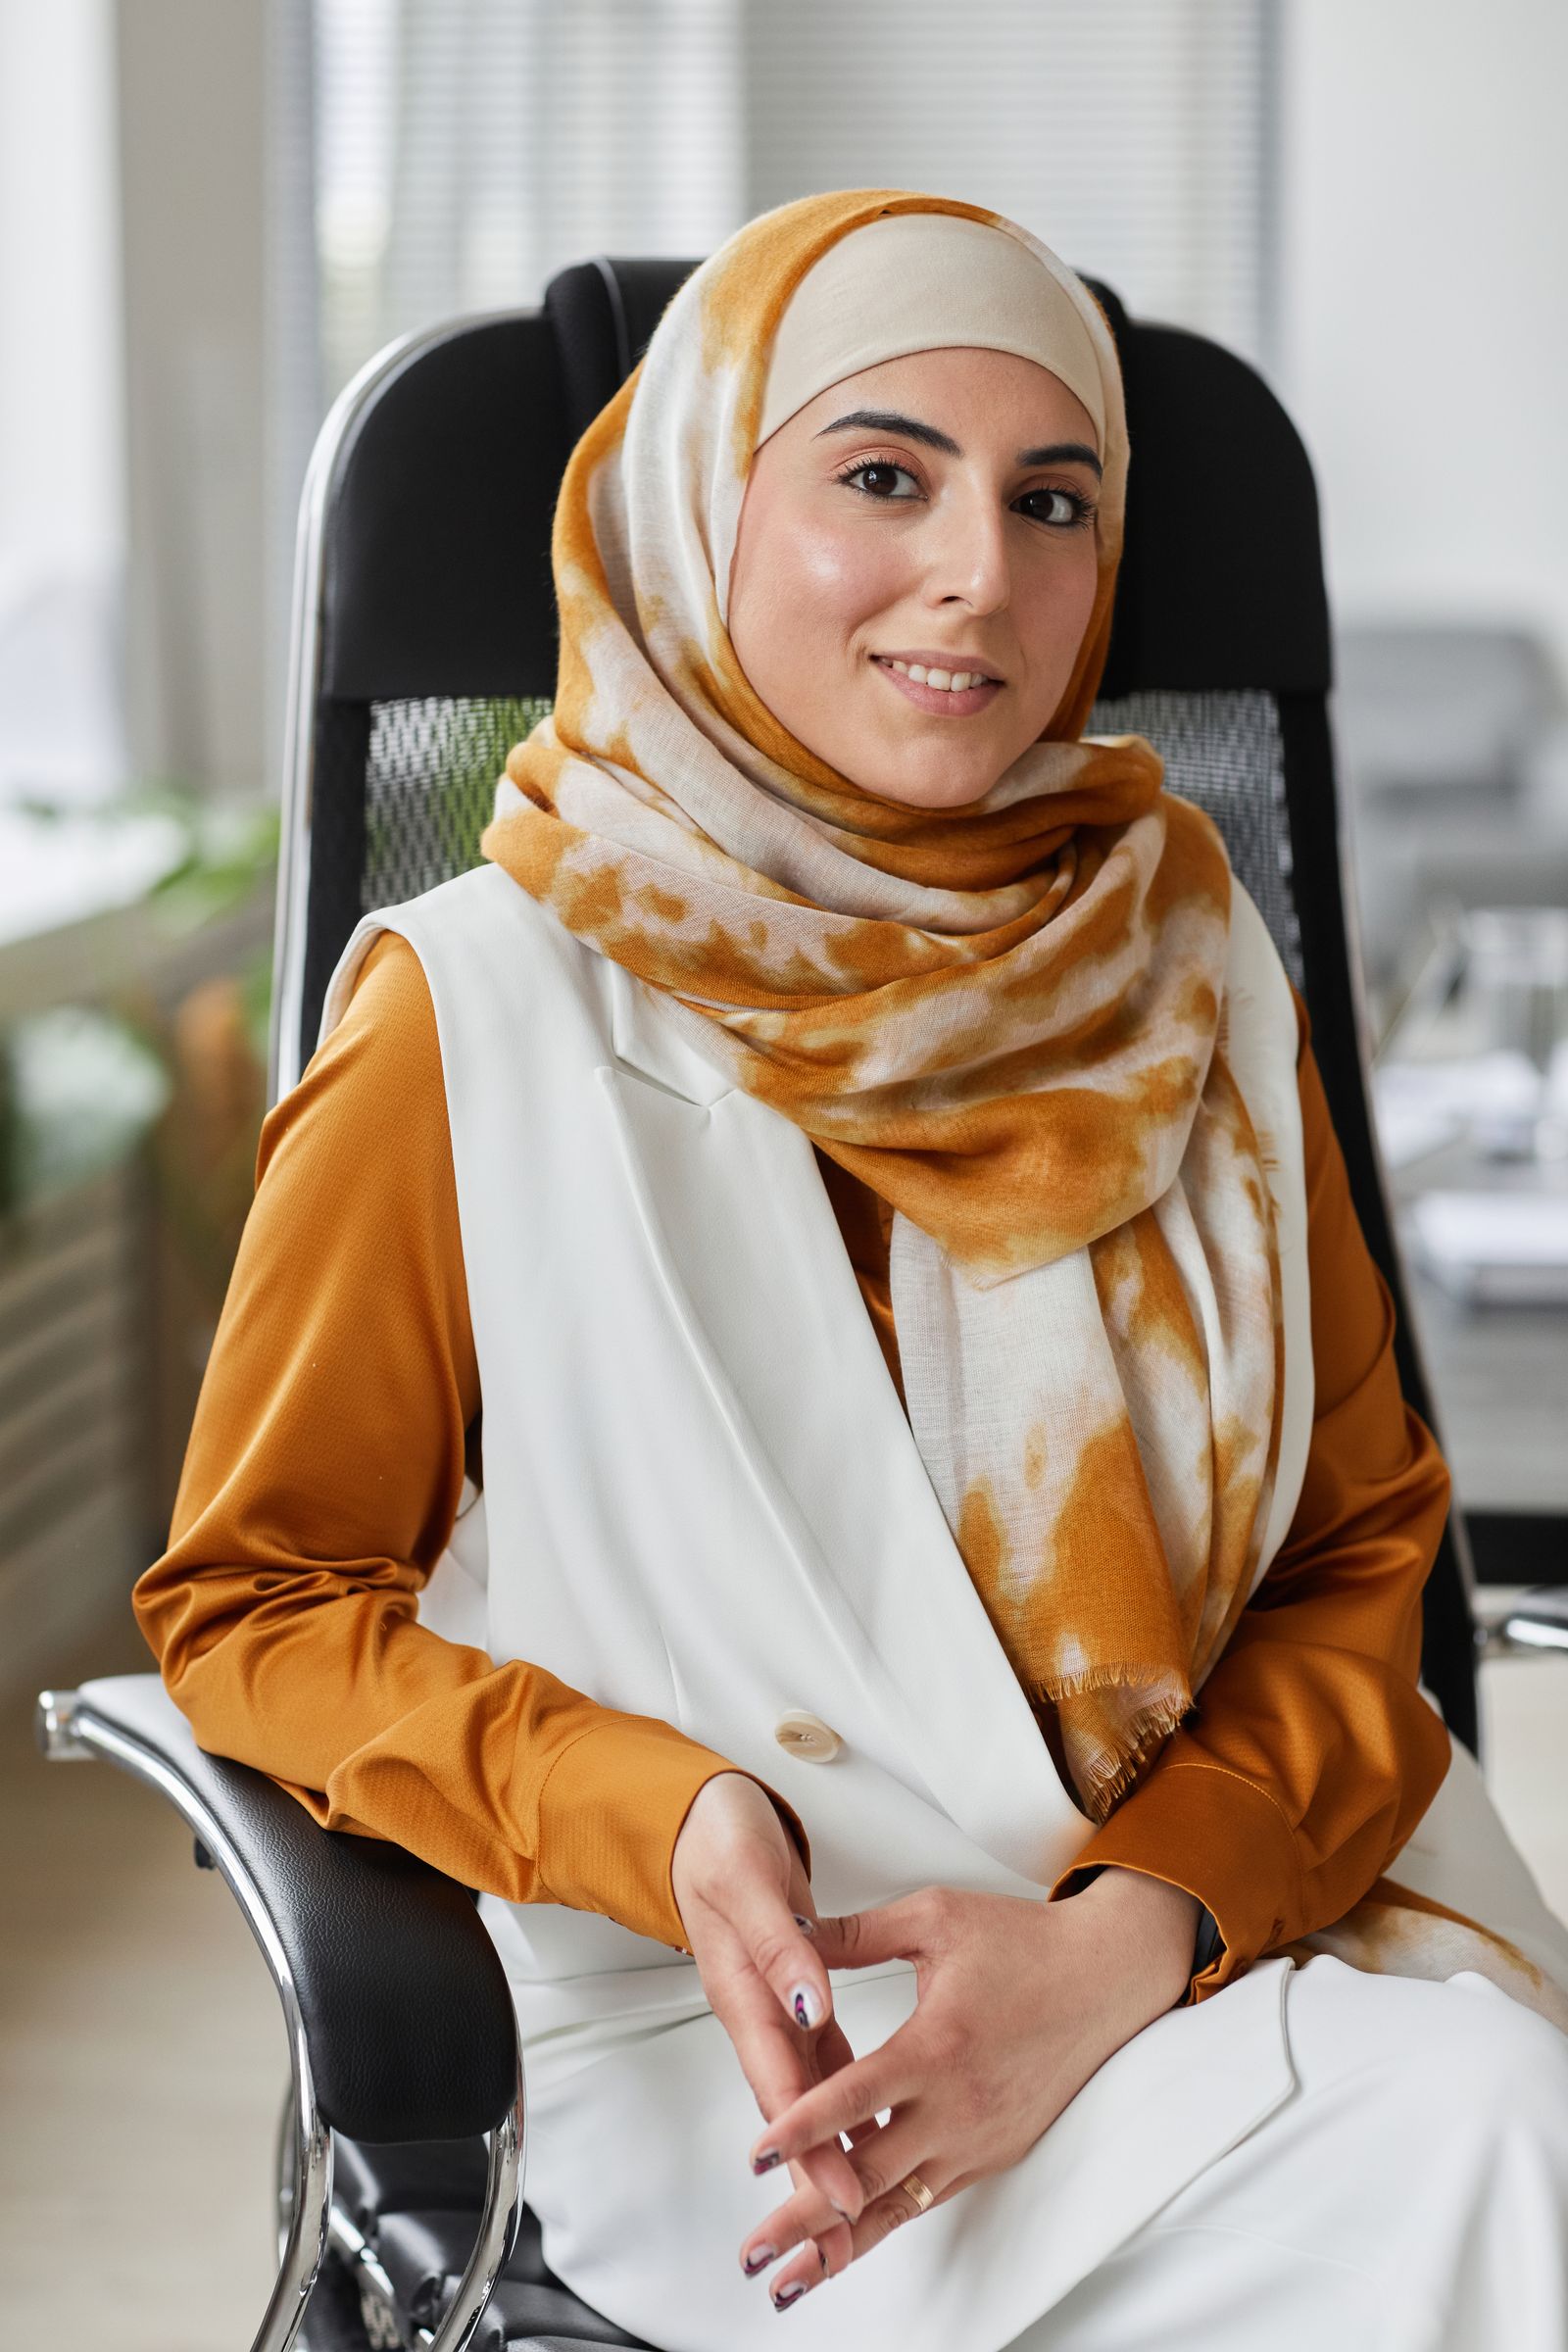
Amira has processed more than 1,100 files. She builds the condition list the day the approval lands and chases title, escrow and insurance so you are not the one following up.
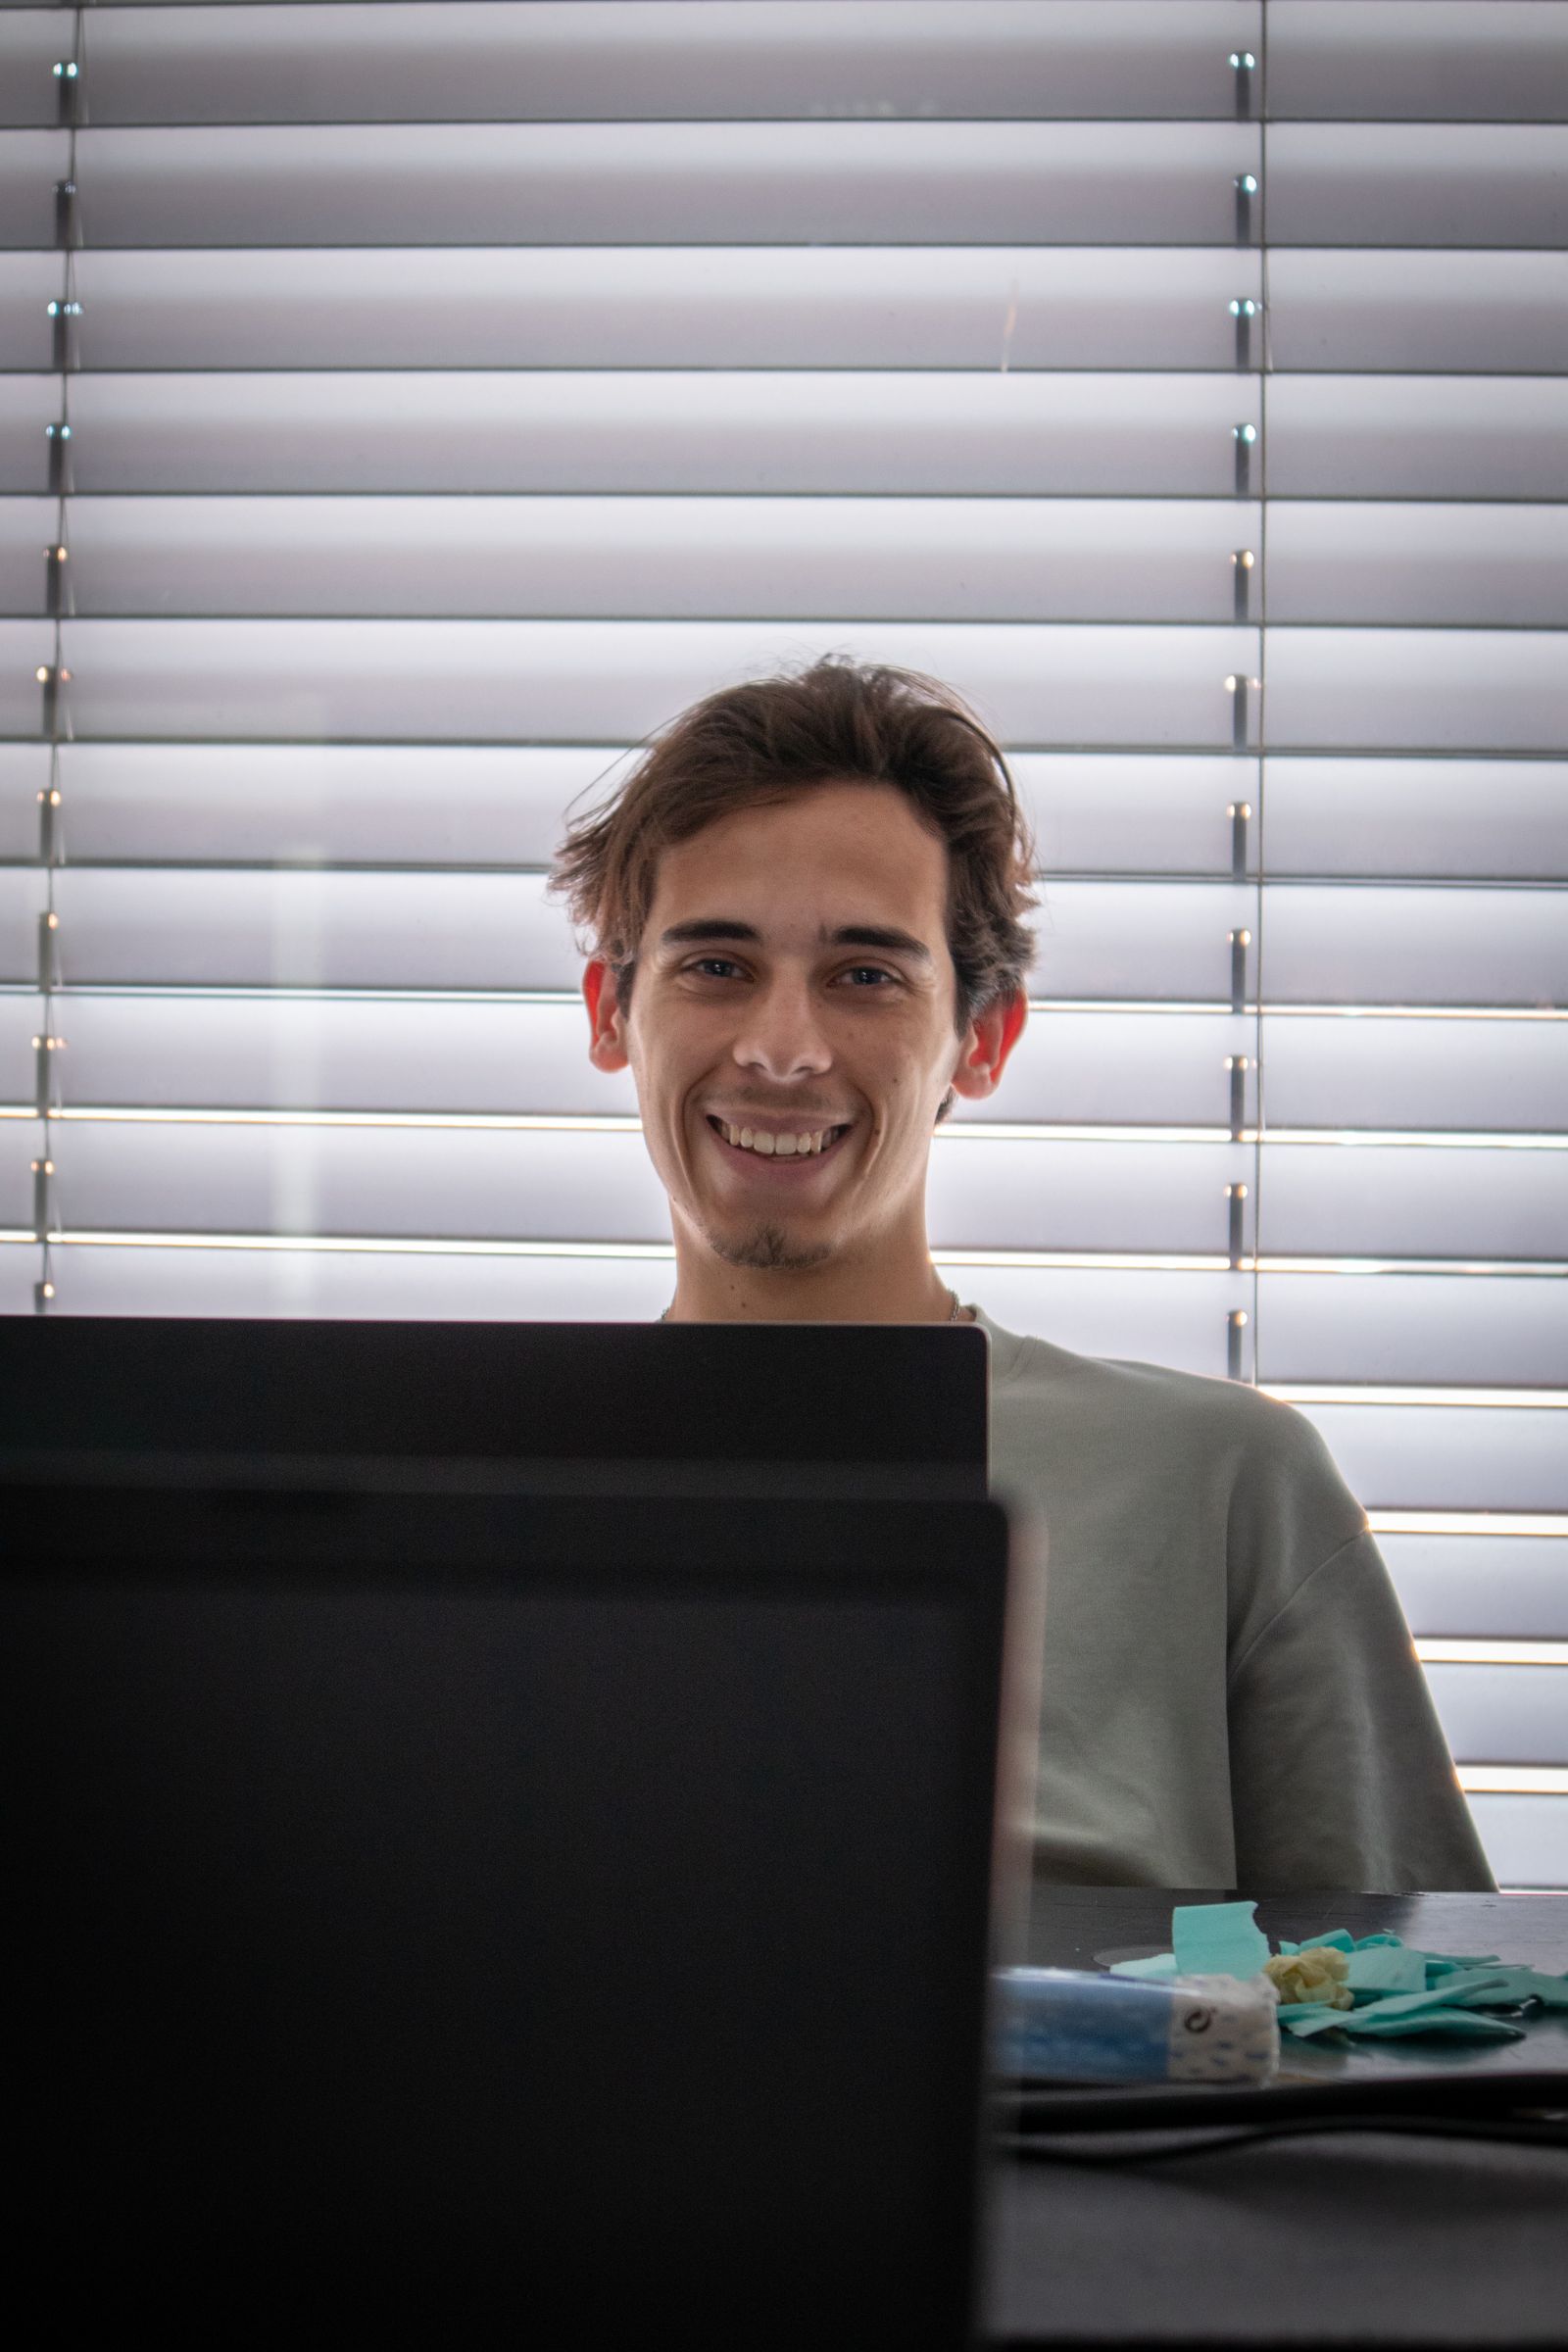
Josh sets up your secure portal, tells you exactly which statement pages are needed and which are not, and answers the small questions quickly so they never turn into delays.
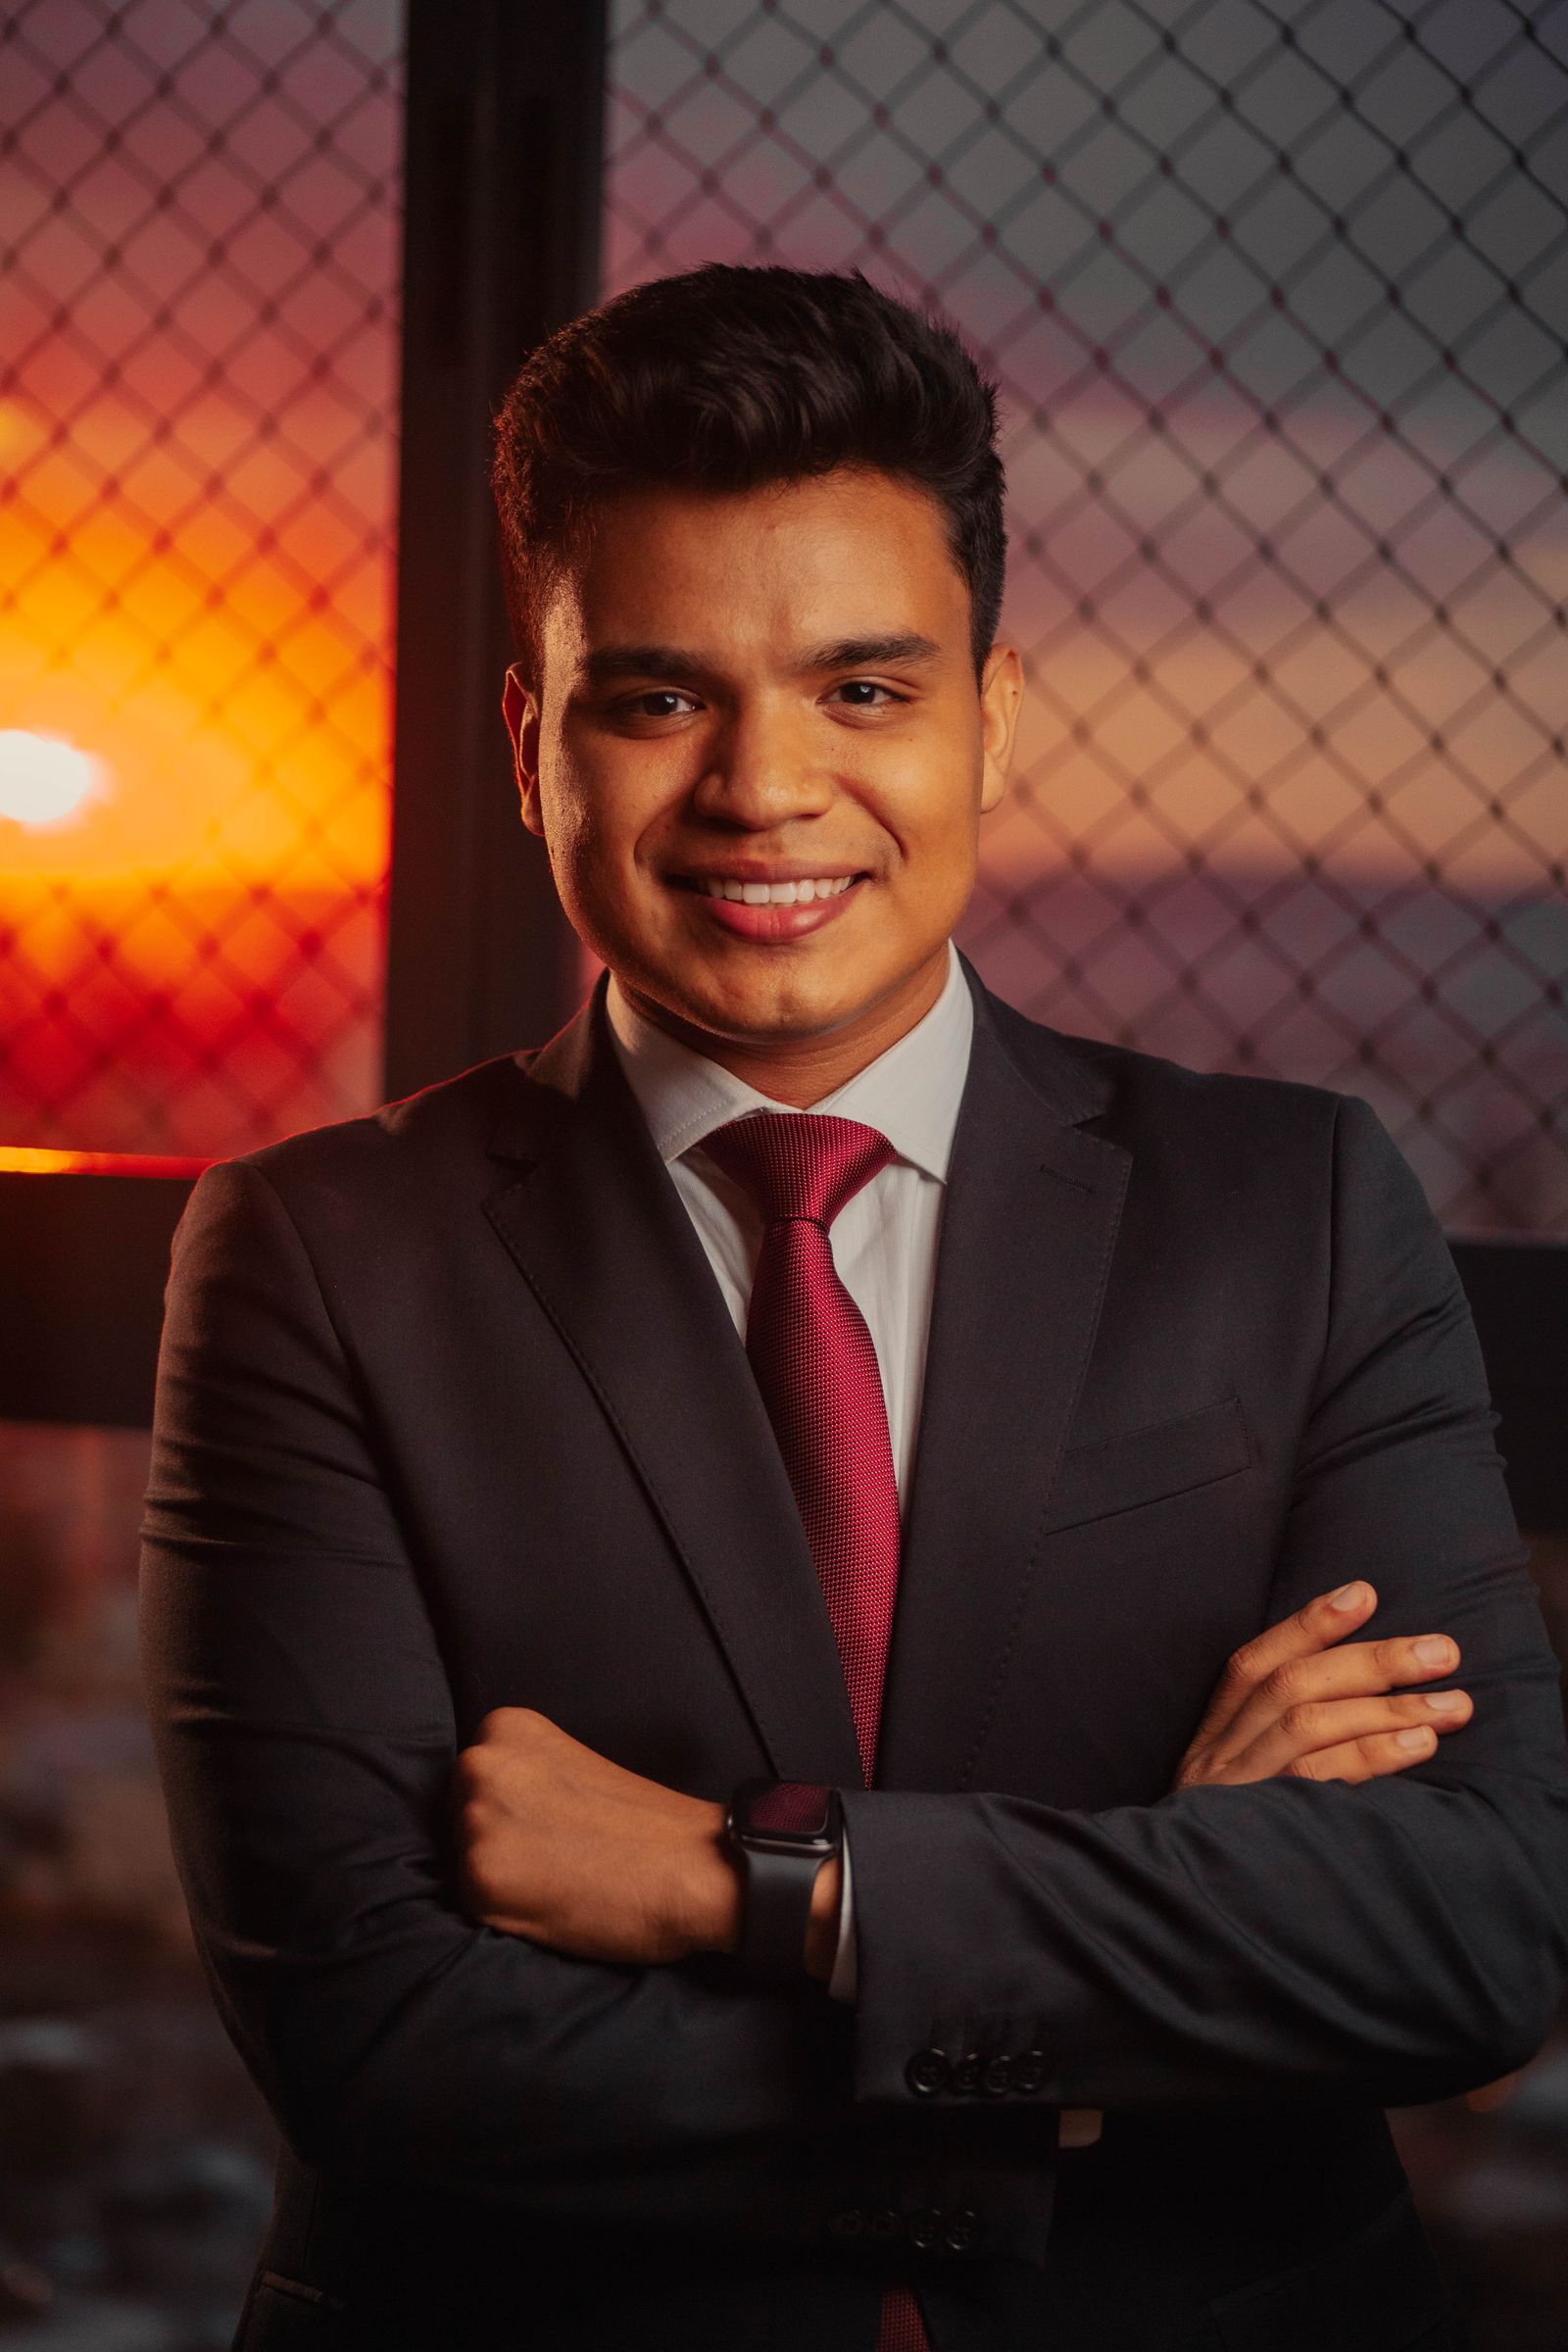
Nikhil watches appraisal, contingency and signing dates against the contract so your agent always knows where the loan stands without having to ask.
Six cities, six different underwriting conversations. Pick yours and you will find sample price figures, the loan programs that fit and the local details that slow files down.
Evening and Saturday slots, or a video call if that is easier.
Wherever we meet, you get the same hour: your numbers, your options and a straight answer about what is realistic.
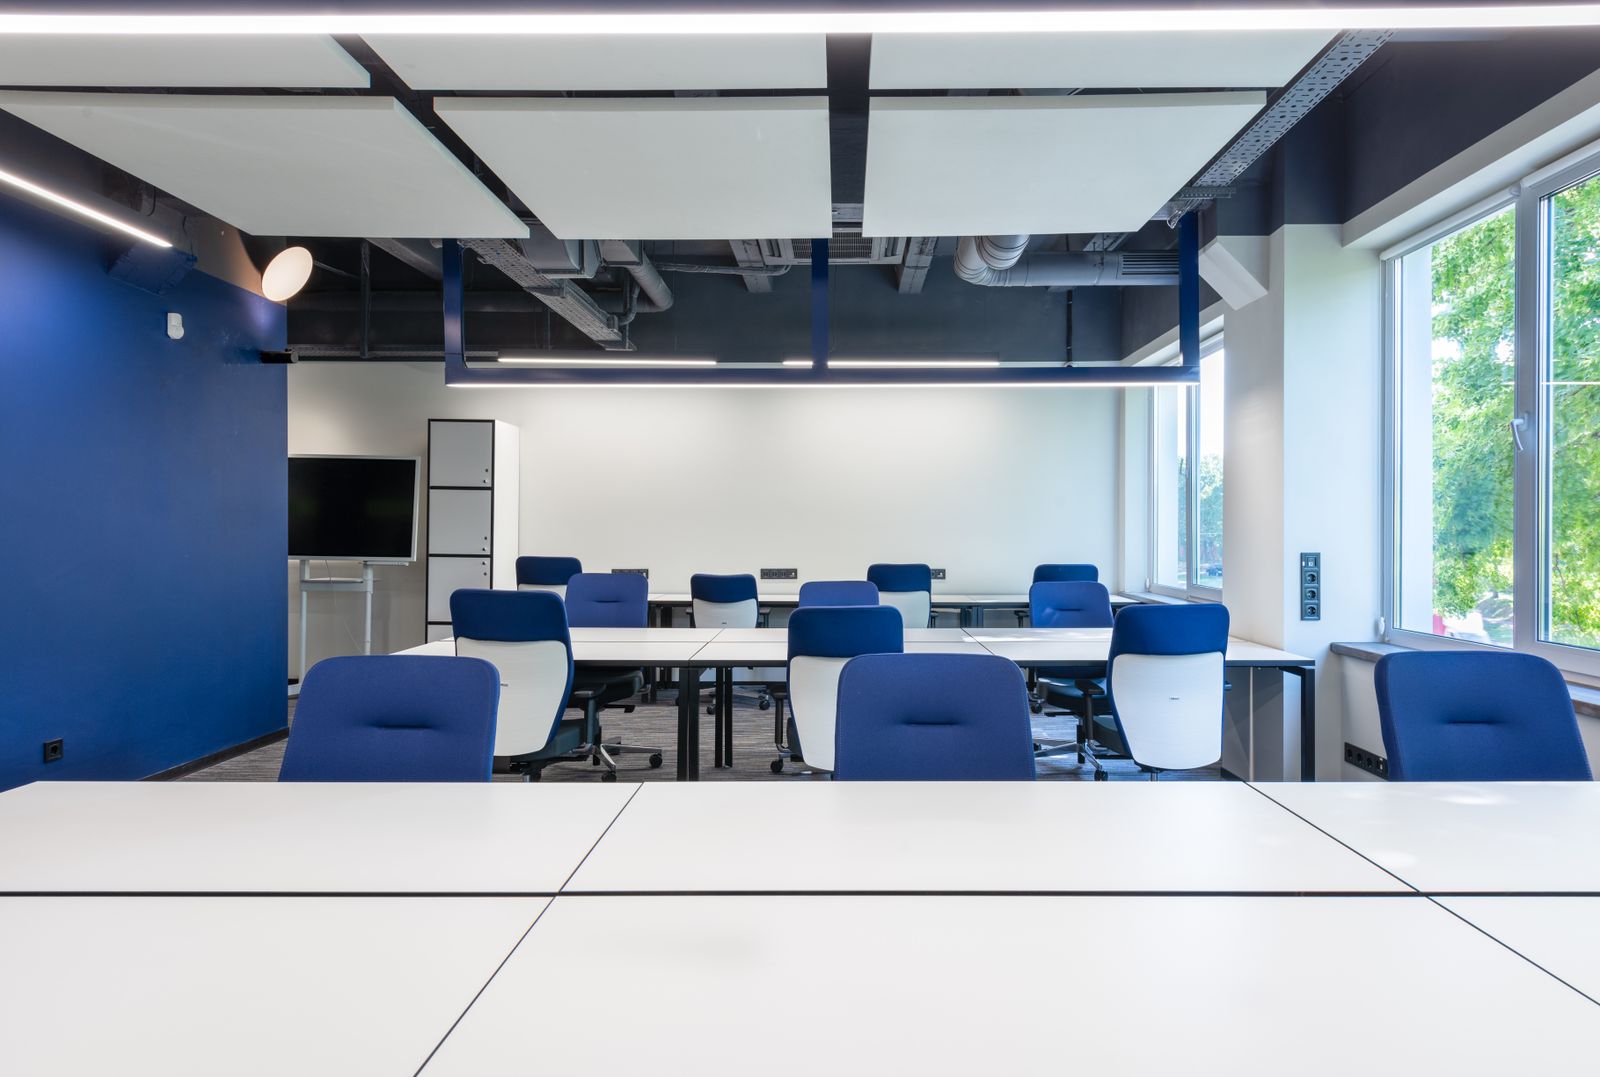
2150 North First Street, Suite 320, San Jose, CA 95131
Today: 8:30 am to 6:30 pm
Free parking in the garage, a whiteboard for the numbers and coffee that is genuinely fine. Best for first meetings with family involved.
Zoom, Meet or a plain phone call
Weekdays to 6:30 pm, Saturdays to 2 pm
Most clients pick this. Screen sharing makes the numbers easier to follow than any PDF, and we can record it for your partner.
Santa Clara, Sunnyvale, Cupertino, Campbell, Los Gatos
Evenings by arrangement
If it is easier to meet near your office or after a showing with your agent, say where and I will come to you.
If yours is not here, ask it on a call. I answer the awkward ones too.
Call (408) 555-0124 or book a 20 minute slot. No documents needed for the first conversation.
Yes, with a two year history of receipt and a vesting schedule that continues at least three years past closing. Most of my lenders use a two year average at a trailing share price. Guidelines differ, which is exactly why lender selection matters on these files.
A pre qualification is a conversation. A pre approval means I have pulled credit, reviewed income and assets, and had an underwriter approve the file. In Santa Clara County the second one is what makes an offer competitive.
No. Every rate, APR and payment shown here is a sample figure for a demo website. Real pricing changes daily and depends on your credit, loan size, property, occupancy and term. Ask me for a written quote and you will get one the same day.
Twenty one days is normal on a clean file, and I have closed in fifteen when an appraisal was waived. Government loans and renovation loans run longer, usually 30 to 45 days.
You work with me. Amira handles processing and Josh handles document collection, and you will meet both, but the calls, the strategy and the hard conversations are mine.
Yes. Conventional programs start at 3% for first time buyers, FHA at 3.5%, and jumbo programs at 10% up to roughly $1.5 million. Mortgage insurance applies below 20% on conventional loans and can be removed later.
A 20 minute call, no documents needed, no pressure to apply at the end of it.
Sample figures across this site are illustrations, not quotes. Equal Housing Opportunity.
We value your privacy
We use cookies to run this site, remember your preferences and understand how it is used.Cookie policy